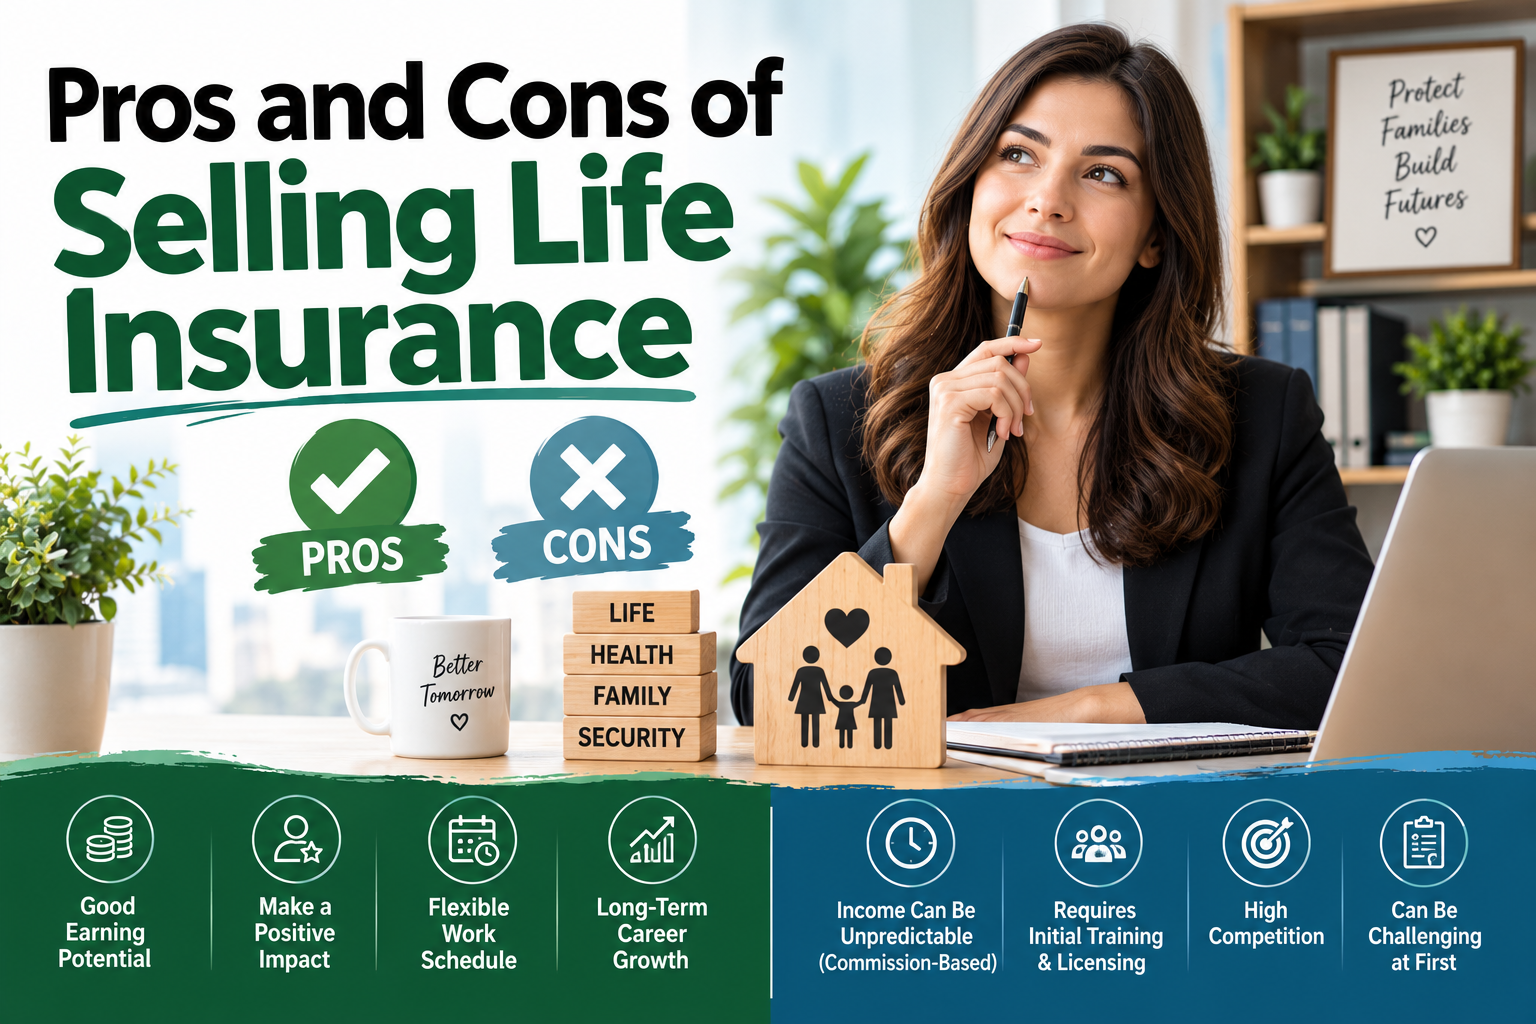
Selling life insurance can be a rewarding career for people who enjoy sales, building relationships, and helping families prepare for the future. It offers potential earning opportunities, career advancement, and, in some roles, flexible working arrangements.
However, the job also comes with challenges, including unpredictable income, licensing requirements, and the pressure to meet sales targets. Understanding the pros and cons of selling life insurance can help you decide whether this career aligns with your skills, financial goals, and preferred working style.
Pros of Selling Life Insurance
1. Potential for High Earnings
One of the main advantages of selling life insurance is the potential to earn commissions based on sales. Depending on the agency and compensation plan, agents may also receive performance bonuses or renewal commissions on eligible policies.
As you gain experience and develop a client base, your earning opportunities may grow. However, actual income depends on sales performance, commission rates, policy retention, and the terms of your contract. High earnings are possible but not guaranteed.
How important are your sales performance?
2. Meaningful Work
Life insurance helps families prepare for financial responsibilities if an insured person passes away. Agents can make a meaningful difference by helping clients understand their coverage options and choose policies suited to their needs.
For people who value relationship-building and financial education, this can be one of the most fulfilling pros of selling life insurance.
3. Opportunities for Career Growth
Insurance sales can provide a path into senior sales, training, or management roles. Some agencies allow experienced agents to mentor new hires or take on leadership responsibilities.
These opportunities may help you develop communication, negotiation, customer service, and leadership skills that are useful in other careers, too.
Visit HMG Careers for the right opportunities for your career.
4. Flexible Working Arrangements
Depending on the agency, agents may work remotely, conduct virtual appointments, or have some control over their schedules. This flexibility can reduce commuting and make it easier to organize your workday.
However, flexibility does not necessarily mean fewer hours. Client appointments, follow-ups, and sales targets can still require a consistent time commitment.
Cons of Selling Life Insurance
1. Unpredictable Income
A major disadvantage of selling life insurance is that commission-based roles may not provide a consistent paycheck. Sales can fluctuate from month to month, particularly when you are new and still building a client base.
If you have regular bills or limited savings, consider whether you can manage periods of lower earnings before accepting a commission-only position.
2. Rejection and Sales Pressure
Not every prospect will be ready to buy a policy. Agents often need to follow up repeatedly, answer objections, and explain the value of coverage without making clients feel pressured.
Meeting targets while handling rejection can be stressful, especially for people who prefer predictable tasks over sales-driven work.
3. Licensing and Ongoing Education
In most jurisdictions, agents must obtain the appropriate license before selling life insurance. Requirements vary but may include pre-licensing education, examinations, licensing fees, and continuing education.
These requirements take time and may involve upfront expenses. Agents must also keep up with product details, regulations, and industry practices.
HMG Careers has a thorough plan for you to get your license
4. Building Trust Takes Time
Life insurance involves personal finances and sensitive family decisions. Prospective clients may need time to compare policies, understand costs, and decide how much coverage they need.
Success requires patience, clear communication, and product knowledge. Agents who focus only on closing sales rather than understanding client needs may struggle to build long-term relationships.
A guide to building and maintaining client relationships
Pros and Cons of Selling Life Insurance: A Summary
Swipe sideways if needed to see all columns.
| Pros | Cons |
|---|---|
| Potential to earn commissions and bonuses | Income may fluctuate |
| Opportunity to help protect families financially | Frequent rejection and sales pressure |
| Career advancement into leadership roles | Licensing costs and ongoing education |
| Flexible or remote work in some positions | Finding and retaining clients takes time |
| Potential renewal commissions on eligible policies | Earnings may depend heavily on performance |
FAQs
Is selling life insurance a good career?
Selling life insurance can suit people who enjoy sales, communicating with clients, and working toward performance-based goals. Whether it is a good career depends on your financial needs, the compensation plan, training, and ability to manage rejection.
Is selling life insurance difficult?
It can be challenging because agents need to understand insurance products, find prospective clients, handle objections, and meet sales goals. Training and consistent practice can help build confidence and improve performance.
Do life insurance agents earn a base salary?
Some positions offer a base salary plus commission, while others are commission-only. Always review the offer and ask how commissions, bonuses, and renewal payments are calculated.
Do you need a license to sell life insurance?
Generally, yes. Requirements depend on your state or province and may include pre-licensing education, an exam, fees, and continuing education.
Can you sell life insurance remotely?
Some agencies allow agents to work remotely and meet clients virtually. The available flexibility depends on the employer, client requirements, and performance expectations.
How can I decide whether selling life insurance is right for me?
Consider your comfort with sales, ability to manage variable income, communication skills, and willingness to complete licensing requirements. Before accepting an offer, ask about lead support, training, expenses, commission rates, and realistic earnings.
For example, HMG Careers describes its insurance agent opportunities as commission-based and says it provides training and access to leads. Applicants should verify the details of the specific position before committing.